 Business · Economy 51
Artificial intelligence (AI) is ushering in significant changes across every sector and industry, and some of the companies at the forefront have already been handsomely rewarded for their efforts, with much more to come. But with more and more companies getting in on AI, which ones are worth investing in? Perhaps it might help to take some inspiration from successful investors, such as David Tepper, the billionaire founder of the family office Appaloosa Management.
Appaloosa has several prominent AI stocks in its public equity portfolio, and two of them, Micron Technology ( MU +2.96% ) and Amazon ( AMZN +4.98% ) , account for about 31% of the portfolio. Are these AI stocks worth buying today? Let's find out.
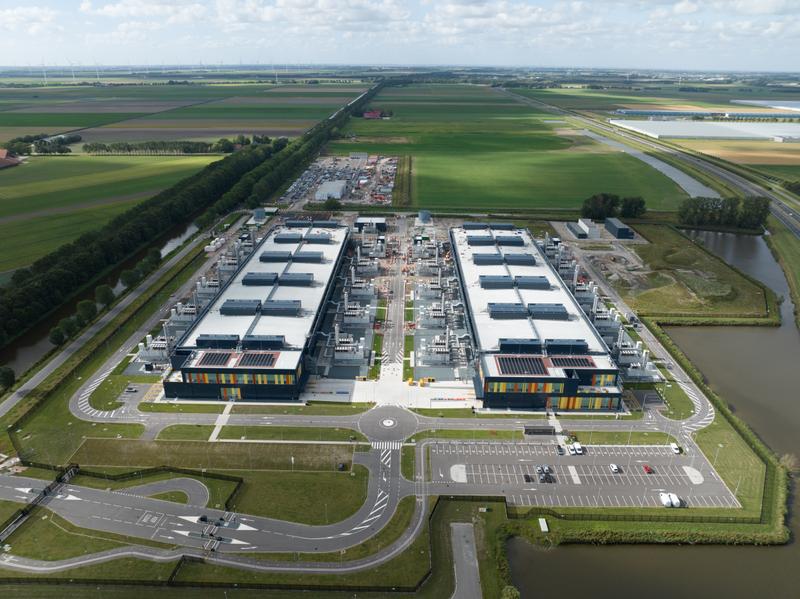
Image source: The Motley Fool. 1. Micron Technology Micron is one of the leaders in providing computer memory and data storage products, such as DRAM (Dynamic Random Access Memory) chips, which are widely used in data centers. The company's shares have climbed a little more than 200% this year as its financial results have significantly improved.
In the fourth quarter of its fiscal year 2026, which ended Sept. 3, Micron's revenue soared by 379% to $54.2 billion. That was more than it generated during its entire fiscal year 2025. MU Micron Technology $904.90 +$26.06 (+2.96%) NASDAQ · As of 4:00 PM ET 10/19/26 The company's non-GAAP gross margin for the period was 87%, substantially higher than the 45.7% reported in the prior-year quarter.
Micron's non-GAAP operating income was $44.6 billion at an 82.3% operating margin, versus $4 billion at 35% in the year-ago period. And Micron posted non-GAAP earnings per share of $33.42, up 1003% year over year. Micron is flying on all cylinders.
But during the second quarter, Appaloosa Management reduced its stake in the stock by about 41%, likely partly to cash in some nice gains. It now accounts for 15.06% of the fund's public equity portfolio, indicating that Tepper and his team remain bullish on the company's prospects. That makes sense.
Micron Technology is benefiting from a shortage of memory chips amid the massive AI build-out, which is granting the company significant pricing power. The shortage could continue at least through 2028, according to some projections, and Micron sees significant demand through that year. Micron's incredible sales and earnings growth will eventually slow and normalize.
But note that the market is arguably already factoring that in. The company is trading at just 7x forward earnings, versus an average of 19.7x for information technology stocks. At current levels, Micron's shares remain attractive. 2.
Amazon Amazon was the largest holding in Appaloosa Management's public equity portfolio as of the second quarter, accounting for almost 16% of the portfolio. What's more, during the period, Tepper and his team increased their stake in the conglomerate by about 15.7%. That was, in my view, a good move.
Amazon is performing well. Second-quarter revenue jumped 20% year over year to $200.6 billion, while the company's net earnings per share came in at $5.75, up 242% from the year-ago period (in fairness, Amazon's EPS included a positive impact from equity investments). AMZN Amazon $262.45 +$12.45 (+4.98%) NASDAQ · As of 4:00 PM ET 10/19/26 Amazon's cloud business , Amazon Web Services, performed particularly well.
It posted net sales of $42.2 billion, up 37% year over year. The company's AI business is playing a key role here, and there is more where that came from. Amazon is guiding for $220 billion in capex this year, up from its previous projection of $200 billion (the increase was partly due to higher memory prices).
That's a significant sum, but Amazon appears to be in a strong position to monetize its investments over the medium term. The company already has cloud demand visibility through 2028, for instance. Even beyond its cloud business, though, Amazon has attractive growth opportunities.
The company's high-margin advertising segment continues to grow at a good clip, while it is looking to make productivity and margin gains within its largest segment by sales -- e-commerce -- notably through AI-powered initiatives. Amazon has performed more or less in line with broader equities this year, and over the next five years, the company is well-positioned to deliver strong returns.
Source: The Motley Fool